EIN & Tax IDs
Form SS-4 for International Applicants: A Practical Guide
Work through the key sections of Form SS-4, with special attention to foreign responsible parties, LLC classification and submission destinations.
Form SS-4 is the IRS application for an Employer Identification Number. For an international founder, the difficult parts are usually the responsible-party information, the LLC's tax classification and the correct submission route.
This walkthrough focuses on a US state LLC with an owner outside the United States. It helps you prepare the facts for the form; it is not a completed template suitable for every foreign applicant.
Checked 5 October 2026 against Form SS-4 and its December 2025 instructions. Always download the current IRS version when you apply.
Before filling in Form SS-4
Have the approved LLC formation document, ownership details, mailing and physical addresses, principal business activity and any existing EIN information available. Identify the individual who actually controls the entity and its funds.
Download the official Form SS-4 and keep the IRS instructions beside it. Use the form's own eligibility and line-completion rules if your circumstances differ from this guide.
Do not fill blanks by copying another founder's application. Two businesses formed in the same state can need different answers because their ownership, employees or tax elections differ.
Lines 1–6: establish the entity and its addresses
Use the legal name from the approved formation record on line 1. A different trading name belongs in the trade-name field where applicable; it should not replace the legal entity's name.
Distinguish the mailing address from the actual street address. The form permits foreign address information, while the street-address field is not for a PO box. The principal business location should reflect the facts rather than automatically copying the registered-agent address.
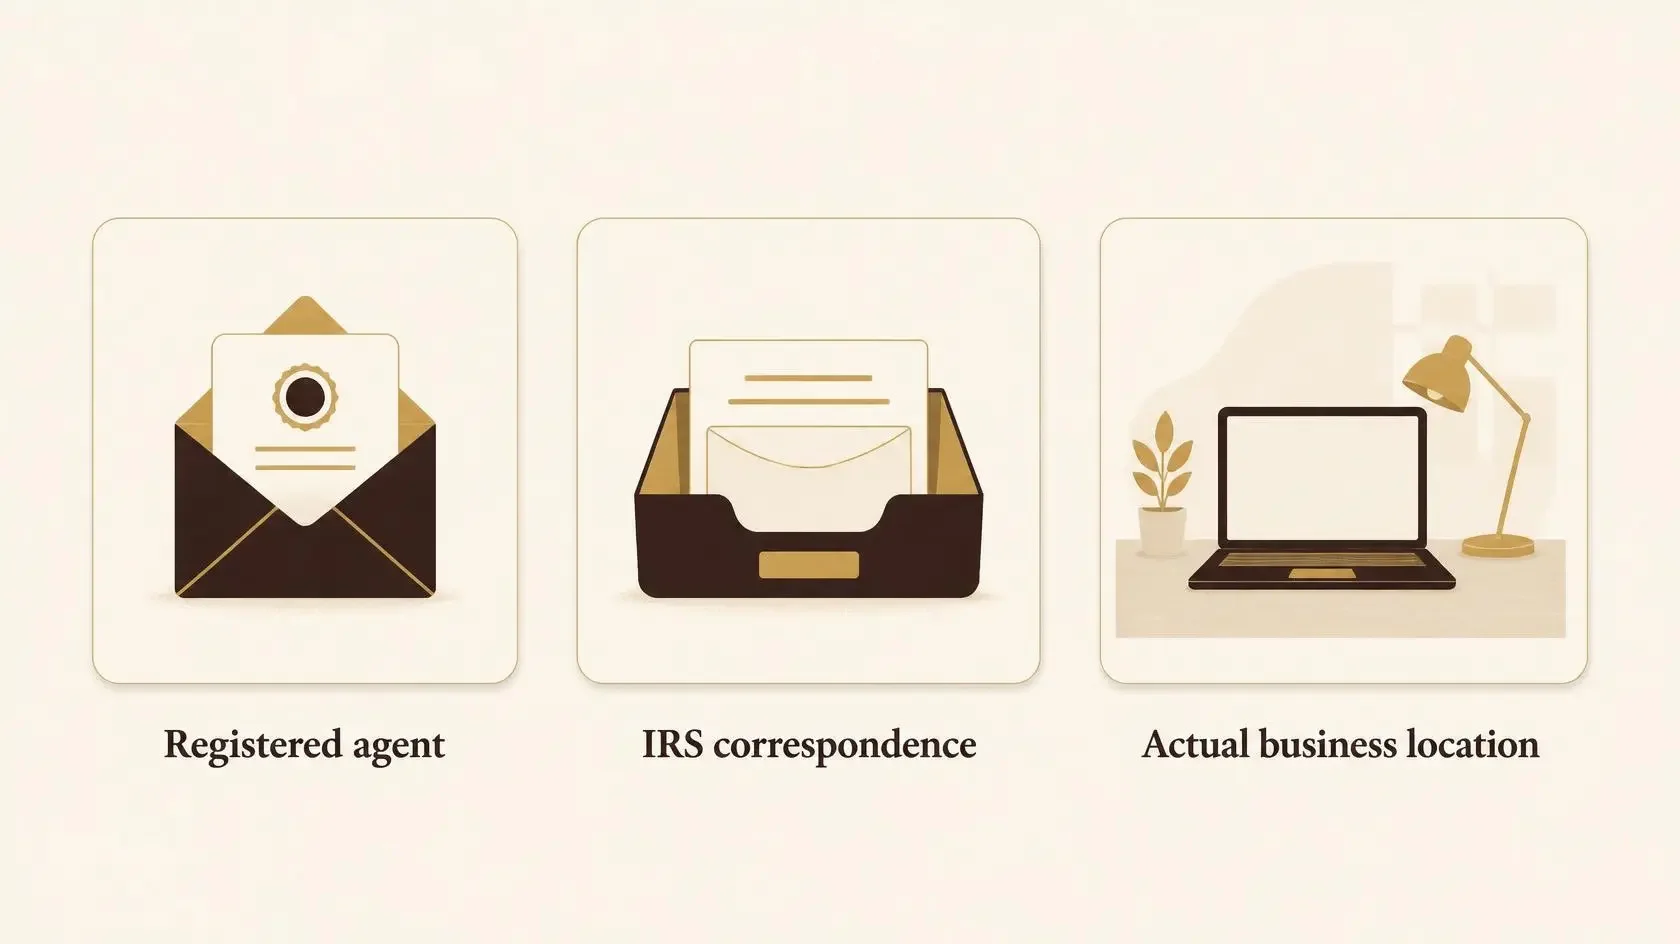
For your own review, prepare three separate labels before typing anything: “state registered agent,” “IRS correspondence address” and “actual business location.” Sometimes addresses overlap, but they do not have identical purposes.
Confirm that you can receive correspondence at the address you provide. If someone else receives it for you, agree how it will be forwarded and how you will be told when it arrives.
Lines 7a–7b: identify the responsible party correctly
Line 7a concerns the responsible party, not merely the person who types or submits the form. A third-party helper is not automatically that person. IRS responsible-party rules.
For line 7b, the foreign exception applies only when the responsible party has neither an SSN nor an ITIN and is ineligible to obtain either. The IRS then permits “foreign” or “N/A.” Do not invent a number, substitute a friend's identity or assume that residence overseas proves eligibility for this exception.
If the responsible party already has an applicable ITIN, do not conceal that fact by following a generic “no SSN” example. Resolve the identification question before submitting.
Lines 8a–8c: separate ownership from formation location
These fields identify whether the applicant is an LLC, its member count and whether it was organized in the United States. A Wyoming or Delaware LLC is US-organized even if its sole member lives overseas.
Count legal members accurately. A service provider assisting with registration is not an extra member simply because it filed the paperwork. Compare the answer with your operating agreement and ownership records.
Line 9a: explain the tax classification
The IRS's default treatment generally differs between a domestic single-member LLC and a domestic LLC with multiple members. Corporate elections can change that treatment. IRS LLC classification overview.
For a foreign-owned US disregarded entity requesting an EIN to file Form 5472, the SS-4 instructions specify the “Other” box with “Foreign-owned U.S. disregarded entity-Form 5472.” This is a particular instruction for that situation, not a phrase to paste into every LLC application.
If the company has multiple members or a corporate election, establish the correct classification first. Completing SS-4 is not itself a tax-classification election. Line 9b has its own corporation-specific instruction; do not populate it simply because a state name seems relevant.
Lines 10–12: reason, starting date and accounting year
Choose the genuine reason for the application. “Banking purpose” is not a universal answer for every founder hoping to open an account. A new operating business and an entity seeking an identifier for a specific filing need can have different circumstances.
Use the applicable business start or acquisition date under the instructions and confirm the accounting year-end. Maintain a note explaining these answers so a later bookkeeper or preparer does not have to reconstruct what you intended.
Lines 13–15: employees and wages
The form asks for the highest number of employees expected in the next twelve months, broken into categories. It directs applicants with no expected employees to enter zero and skip line 14.
Do not check an employment-tax option just because a tutorial does. If you expect workers, determine their status and the applicable payroll obligations. The wage-date question also contains a separate note for certain withholding agents, so review the full instruction where relevant.
Lines 16–18: business activity and previous EIN
Choose the activity that best describes the business and provide a useful description of what you actually sell or do. “Business services” may communicate less than “website development for small retail businesses,” if the latter is accurate.
Check your records before answering whether the applicant has previously received an EIN. If a formation service already applied, obtain the application status before starting another request. An application for the same entity should not be duplicated merely because a confirmation has not arrived.
Third-party designee and signature
The designee section authorizes a named person for the specific EIN-related functions described on the form. It is different from naming the responsible party and is not a general authorization to act for the company indefinitely.
Review the finished application, complete the required signature and contact fields, and save a legible signed copy. Ask any helper for that copy rather than keeping only a payment receipt.
Where should an international applicant send SS-4?
The IRS bases the route on the applicant's location circumstances, not solely the owner's nationality. Its current fax instructions distinguish:
| Applicant circumstances | IRS fax destination |
|---|---|
| Legal residence, principal business, principal office or agency in a US state or DC | 855-641-6935 |
| No such presence in a US state or DC; fax sent from within the US | 855-215-1627 |
| No such presence in a US state or DC; fax sent from outside the US | 304-707-9471 |
For mail, applicants with the US-state/DC presence described above use Internal Revenue Service, Attn: EIN Operation, Cincinnati, OH 45999. Applicants without that presence use Internal Revenue Service, Attn: EIN International Operation, Cincinnati, OH 45999. Check the current instructions before posting the signed application.
The international telephone route applies when the applicant has no legal residence, principal business, principal office or agency in the United States or its territories. The current number is +1 267-941-1099, Monday–Friday, 6 a.m.–11 p.m. Eastern Time; it is not toll-free. The caller must be authorized and able to answer the SS-4 questions. Do not assume every foreign owner qualifies for this route simply because the owner is abroad.
Recheck the IRS “How To Apply” instructions immediately before sending. Fax numbers can change, and a number used for a different IRS filing is not an alternative EIN destination.
Final review before submission
Compare the legal name with the state document, the ownership with company records and the addresses with their actual purposes. Confirm line 7b eligibility, line 9a classification, a genuine reason for applying and the required signature.
Keep the application, submission evidence and subsequent IRS correspondence together. Use one application route and follow up on that application rather than submitting duplicates.
Get help preparing your application
Contact PrimeRegister about EIN assistance. Tell us whether your LLC is already formed, its state, its number of members and your country of residence. We can explain the information needed and the scope of assistance before you share sensitive documents.