International LLC Formation
Can a Foreign Company Own a US LLC? Structure Guide
Can a foreign company own a US LLC? In many ordinary business situations, yes, subject to the applicable state, industry and other legal requirements. But company ownership introduces a different documentation and tax review from a US LLC owned directly by an overseas individual.
Can a foreign company own a US LLC? In many ordinary business situations, yes, subject to the applicable state, industry and other legal requirements. But company ownership introduces a different documentation and tax review from a US LLC owned directly by an overseas individual.
Before filing, decide whether the foreign company or its shareholders should own the new entity. That choice affects who contributes funds, signs agreements and receives distributions. It should not be decided accidentally by whoever fills out the formation questionnaire.
Can a foreign company own a US LLC under state law?
Delaware's LLC framework, for example, recognizes members through a definition of persons that includes domestic and foreign entities. This illustrates entity ownership; it does not establish the rules for every state or regulated business. Delaware LLC definitions.
Confirm the intended state's rules and any restrictions on the actual activity. An ordinary consulting company and a regulated professional practice may not have the same options.
Subsidiary formation is different from registering the parent
A newly formed US LLC
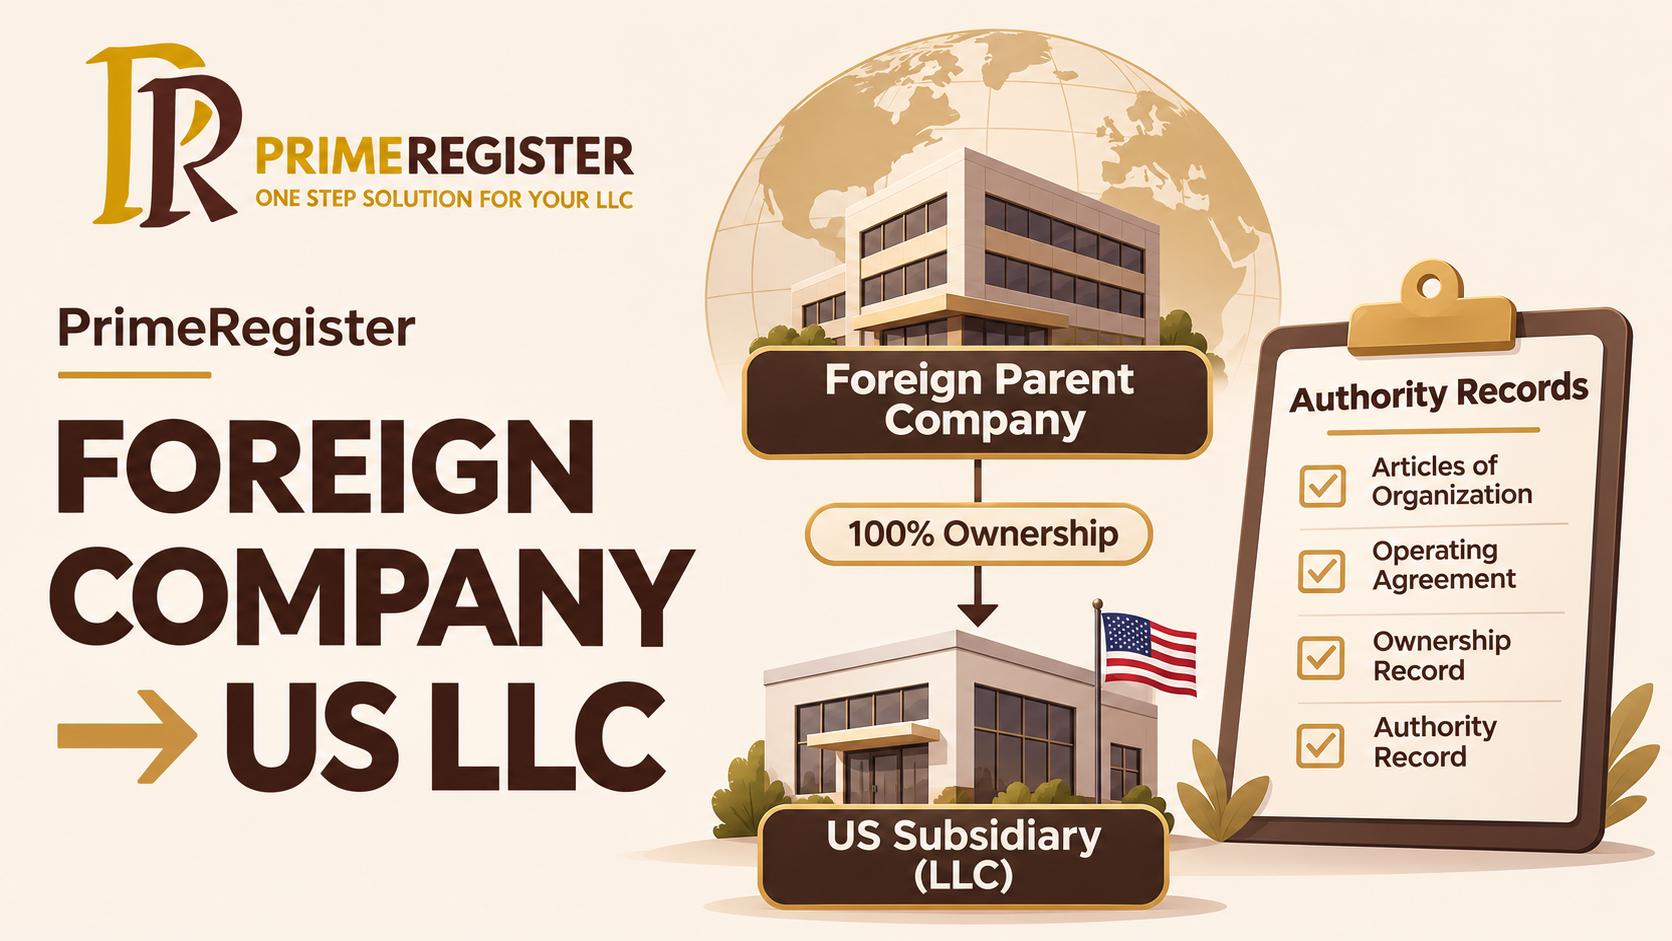
The new LLC has its own entity record, with the foreign company as owner if that is the chosen structure. Documents should show the correct ownership and authority chain.
Registration of the existing foreign company
Registering an existing entity to do business in a jurisdiction is a different legal step from creating a subsidiary. Do not assume one filing performs both jobs. Our foreign qualification versus foreign ownership guide explains the terminology.
Build an ownership and authority file
Prepare a clear chart from the US LLC through the parent to the ultimate owners. Then collect documents that support the chart.
| Document group | Purpose |
|---|---|
| Parent registration records | Establish the parent's legal identity |
| Ownership records | Explain who owns and controls the group |
| Approval or resolution | Record authority for the investment and signatories |
| LLC agreement | Document the subsidiary's ownership and management |
| Funding records | Explain the source and purpose of transferred money |
The exact documents, translations and certification requirements vary by recipient. Ask the bank or provider before purchasing unnecessary certified copies. Our certified LLC documents guide explains the basic distinctions.
A separate legal entity may not be a separate income-tax taxpayer
A single-member LLC can be disregarded by default for federal income tax, while elections can change classification. If the owner is a foreign corporation, the consequences need analysis at that owner's level as well. IRS LLC classification guidance.
Do not assume that placing “LLC” below a foreign parent automatically blocks every US tax or filing consequence for the parent. Obtain a US and home-country review before deciding the structure, funding and intercompany arrangements.
Identify transactions between the entities
List funding, services, licenses, reimbursements, loans and distributions. They should have an intelligible business purpose and appropriate records.
Determine who performs which work
Write down which entity hires staff, contracts with customers, owns intellectual property and incurs costs. A group chart alone does not answer those operational questions.
Expect ultimate-owner verification
Financial providers may need to identify the people behind an entity owner, not only the name of the foreign parent. For example, Wise's verification guidance requires details of natural persons who ultimately own or control entity owners. Wise US verification guidance.
Prepare the chain early. A parent-company certificate without ownership information may leave a provider unable to complete its review.
Budget for the cross-border structure
Include formation and renewals, accounting, professional tax review, document preparation and the work needed to keep parent and subsidiary records aligned. Ask advisers which returns and reports are covered by their engagement and which are separate.
Use our LLC operating-agreement guide to prepare management questions. Contact PrimeRegister for formation assistance once the ownership decision and cross-border tax plan have been reviewed. A clear structure at the beginning is easier to administer than an ownership chain reconstructed after money starts moving.
Research checked 7 November 2026. General information, not individual legal or tax advice. Check current official requirements before acting.