LLC Formation
Member-Managed vs Manager-Managed LLC: How to Choose
Member-managed vs manager-managed LLC describes who runs the company.
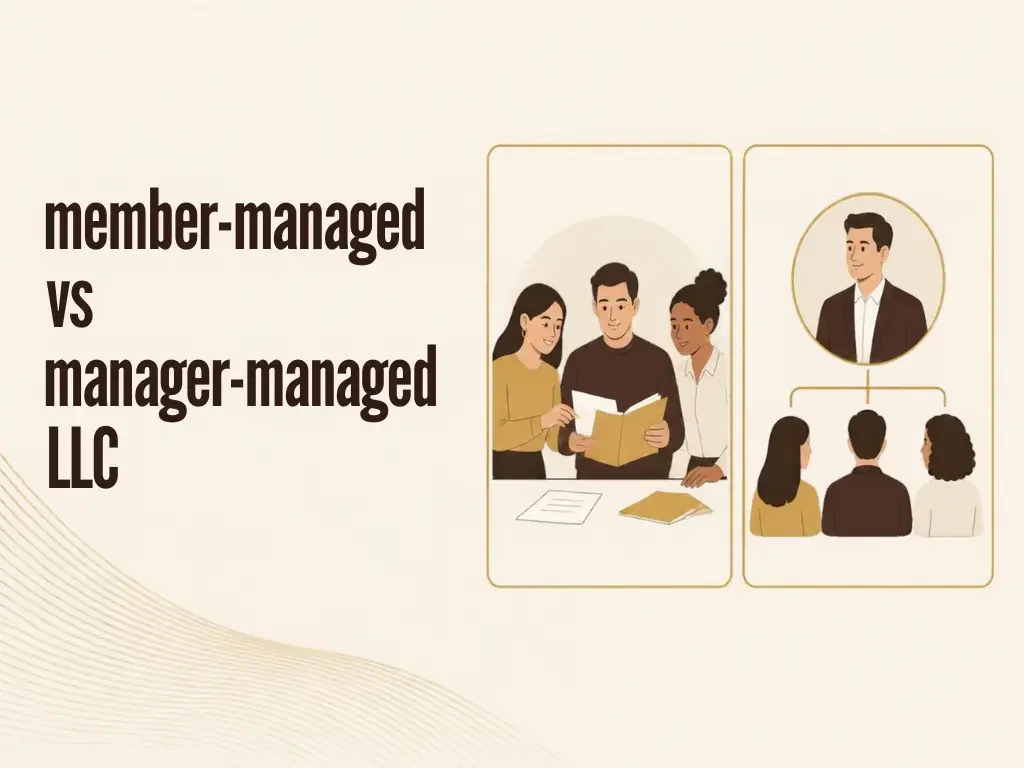
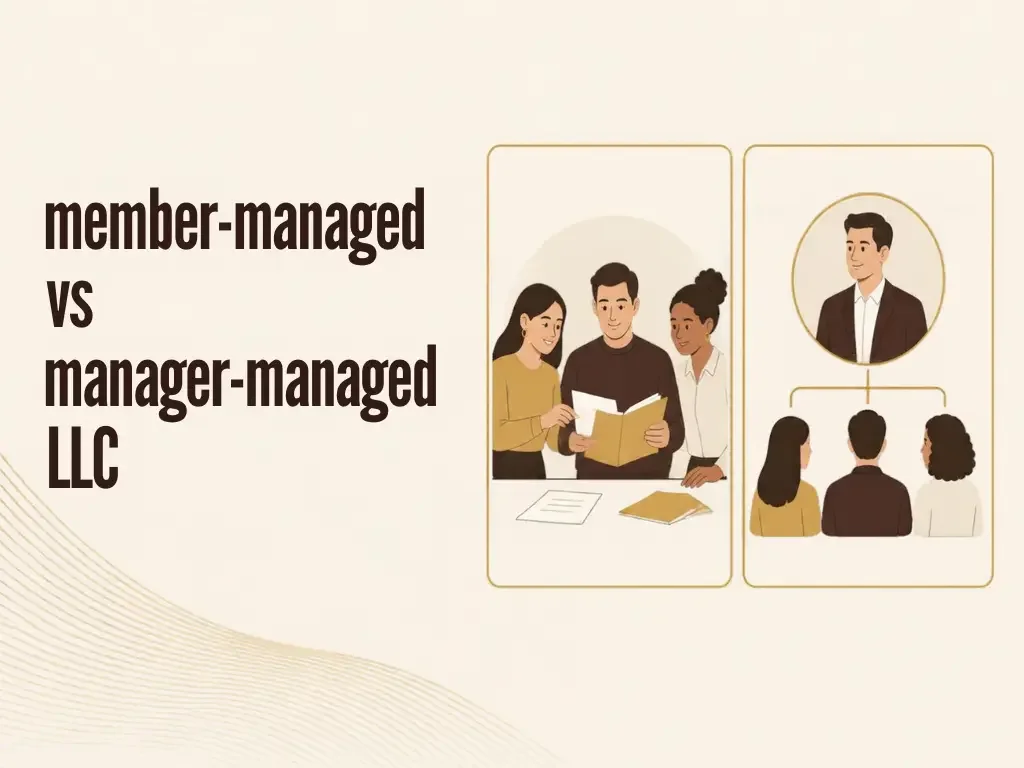
Member-managed vs manager-managed LLC describes who runs the company. In a member-managed structure, the owners participate in management under the agreement and state law. In a manager-managed structure, designated managers handle management, while members retain the rights assigned to them.
This choice does not determine whether an LLC has one owner, whether that owner lives abroad or how the company is taxed.
Member-managed vs manager-managed LLC: compare the decisions
| Question | Member-managed approach | Manager-managed approach |
|---|---|---|
| Who handles operations? | Members under the agreed rules | Designated manager or managers |
| Can ownership be passive? | Requires careful delegation and boundaries | Can separate investment from daily management |
| Where are powers documented? | Agreement and applicable law | Agreement, manager appointment and applicable law |
| What should the bank verify? | Authorized members and signers | Manager authority and authorized signers |
Do not confuse an organizer with a manager. An organizer submits the formation document; that role alone does not make the person an owner or ongoing decision-maker.
Choose based on how the business will actually operate
A solo founder handling contracts and payments may prefer a straightforward management arrangement. A business with several investors and one operating founder may benefit from a clearer division between ownership and daily authority.
However, adding a manager purely to create an appearance of US operations can introduce problems. Appointment should reflect genuine authority and responsibilities. It does not automatically establish tax residency, bank eligibility or a staffed US presence.
Ask who will negotiate contracts, approve invoices, hire people and communicate with providers. If the answers differ, document the boundaries rather than giving everyone an ambiguous title.
State filings and private records must agree
Formation requirements differ by state. Texas's Certificate of Formation asks whether the LLC will have managers and then requests the appropriate initial governing-person information. The Texas Form 205 instructions explain the required distinction.
That is not permission to reuse the Texas form rules in another state. Read the actual filing questions, then make the operating agreement consistent with the selected structure.
Retain any separate manager appointment or member consent. If a bank requests proof of authority, a job title in an email signature may not be enough. Ask the institution which documents it accepts.
The LLC operating agreement checklist helps translate the selected management arrangement into ownership, approval and recordkeeping provisions.
For the rest of the Texas setup process, follow the Texas LLC formation guide; the governing-authority section is only one part of that filing.
Reserve major decisions explicitly
Delegating daily management does not mean every major decision should be unrestricted. Discuss borrowing, selling significant assets, admitting members, changing tax elections and approving transactions with owners or affiliated businesses.
For example, founders might authorize ordinary supplier payments within an approved budget while reserving new debt for member approval. This is an illustrative governance choice, not a clause to copy without checking state law and the agreement.
Also decide what happens when a manager is unavailable. A company should not lose access to essential records simply because one person controls every password or approval.
Management is separate from federal tax classification
The IRS's default classification generally depends on ownership and applicable elections, not the manager-managed label. A domestic LLC with two or more members is generally a partnership by default; a single-member LLC is generally disregarded for income tax purposes unless it elects corporate treatment. Exceptions and separate employment or excise treatment matter. See the IRS LLC overview.
Changing management alone should therefore not be treated as a tax-planning strategy. Ownership changes, elections and cross-border arrangements need their own assessment.
If you are also deciding the legal and tax structure, use the separate LLC vs C corporation comparison before committing to an entity.
Before selecting the formation option
Write a one-page authority list covering contracts, borrowing, payments, bank access and ownership changes. Compare it with the proposed agreement and the state filing. Ask how a future management change must be recorded and whether a state update is required.
Contact PrimeRegister to discuss how the selected management structure will appear in your formation documents. Complex investor or control arrangements should receive tailored legal review before signature.