Tax and Compliance
Foreign-Owned LLC With US Clients: Service Income Taxes
A foreign-owned LLC with US clients does not have a complete tax answer simply because the customers are American. For personal-service income, the location where the work is performed is generally central to determining its source. The payment currency, contract location and payer's residence do not by themselves decide that source.
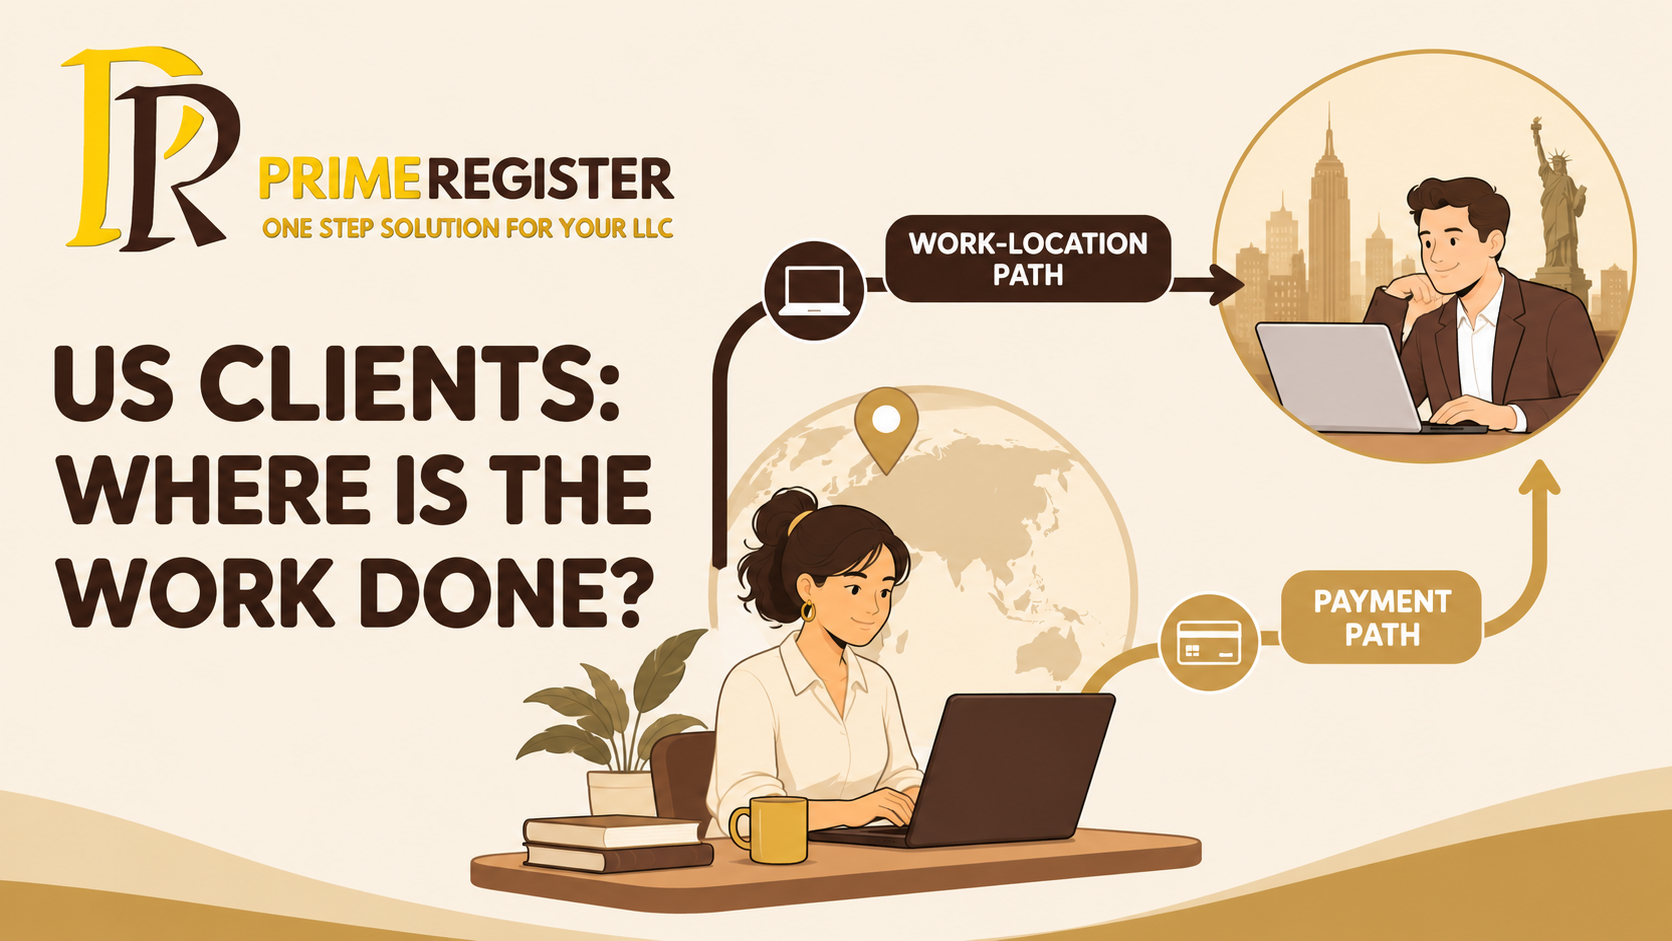
A foreign-owned LLC with US clients does not have a complete tax answer simply because the customers are American. For personal-service income, the location where the work is performed is generally central to determining its source. The payment currency, contract location and payer's residence do not by themselves decide that source.
That does not mean every remotely operated LLC is “tax free.” Income type, entity classification, US business activity and the owner's home-country rules still need review. Use a factual analysis instead of either blanket claim.
Foreign-owned LLC with US clients: start with the service
The IRS generally sources personal-service compensation where the services are performed. Work performed partly inside and partly outside the US requires an appropriate allocation. IRS personal-service income sourcing.
This starting rule is useful for understanding why a US customer alone is not decisive. It should not be copied onto royalties, inventory sales or other income categories without checking their own rules.
Describe the deliverable
Is the customer buying consulting time, a software license, a subscription, intellectual-property rights or physical goods? Similar-looking invoices can represent different transactions. Give the adviser the contract, not only the word “services” in a spreadsheet.
Identify who performed the work and where
Maintain project records, staff locations and travel dates. A founder's overseas residence does not prove that every task was performed overseas if a team or the founder also worked in the US.
Keep three questions separate
| Question | Why it matters |
|---|---|
| What is the income? | Different categories can have different source rules |
| Who is the taxpayer? | Entity classification changes the reporting analysis |
| What US activity occurred? | US trade-or-business and effectively connected income rules may matter |
The IRS explains effectively connected income within the US trade-or-business framework. The result depends on facts, not merely where the customer sends payment. IRS ECI guidance.
Our LLC tax-classification guide is a useful starting point before applying an owner-level conclusion to the business.
A remote-consulting example
Imagine an overseas consultant delivers a project entirely from a home-country office to a US client. The agreement, work logs and invoices support that location. The client pays into a US company account.
The bank's location does not move the consultant's work into the US. However, a preparer must still confirm classification, income character and any additional facts. If the consultant later spends time performing the project in the US, that change belongs in the analysis.
This example illustrates the sourcing question. It does not establish the complete tax position of every consultancy.
Customer tax forms need the correct owner analysis
A customer may request tax documentation during onboarding. Do not select a form solely because the invoice shows an LLC or an EIN. The correct documentation can depend on the payee's tax classification and underlying owner.
Use our W-8BEN versus W-9 guide to prepare questions for the customer and your adviser. Resolve inconsistent forms before they lead to incorrect withholding or information reporting.
No income tax conclusion removes every filing
Company information reporting
Foreign-owner transactions may need review even if an analysis finds no particular US income-tax liability. Do not substitute “no tax due” for a filing checklist. See our Form 5472 guide.
Home-country treatment
Ask a local adviser how the LLC, distributions and retained earnings are treated where you are resident. The answer is not established by the absence of a particular US tax.
State obligations
Review relevant state facts separately. A federal conclusion is not automatically a conclusion about annual reports, registrations or state taxes.
Build a review file you can update
Keep a one-page business description, ownership chart, classification records, customer agreements, work locations, travel dates and reconciled accounts. Update it when the model changes. That makes advice more useful than repeatedly asking whether “a nonresident LLC pays tax.”
Contact PrimeRegister for formation questions, and use the records to obtain a specific tax assessment before relying on a zero-tax claim in your business plan.
Research checked 7 November 2026. General information, not individual legal or tax advice. Check current official requirements before acting.